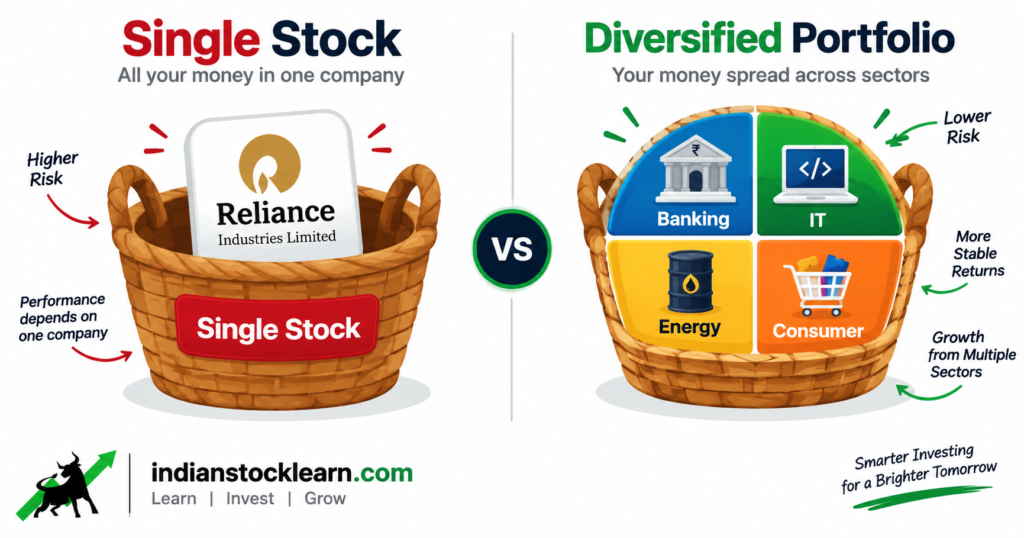
You’ve probably heard “don’t put all your eggs in one basket.” That’s the plain-English version of what is diversification in investing.
Diversification means spreading your money across different companies, sectors or asset types instead of depending heavily on one investment. If one part of your portfolio performs badly, the rest doesn’t automatically go down with it.
This guide covers why diversification is important, how it actually works, where it falls short, and how it shows up in the Indian stock market through examples like the Nifty 50.
- What Is Diversification?
- How Diversification Works
- Myth vs Reality: More Stocks Isn’t More Diversification
- Diversification Formula and Concept
- Real Stock Market Example
- The Look-Through Test: Are You Really Diversified?
- Why Investors Use Diversification
- Advantages and Limitations
- Diversification During a Market Crash
- Your Portfolio Starts Outside Your Demat Account
- Key Takeaways
- FAQs
- Conclusion
What Is Diversification?
Diversification is the practice of spreading investments across different companies, sectors, industries or asset types to reduce dependence on any single investment. In plain words, it means not relying on one investment to do all the work.
Suppose an investor puts ₹1 lakh entirely into one stock. That single company’s performance now decides almost the entire outcome. Spread the same ₹1 lakh across several companies from different industries, and a fall in one still hurts – but its effect on the total portfolio is smaller.
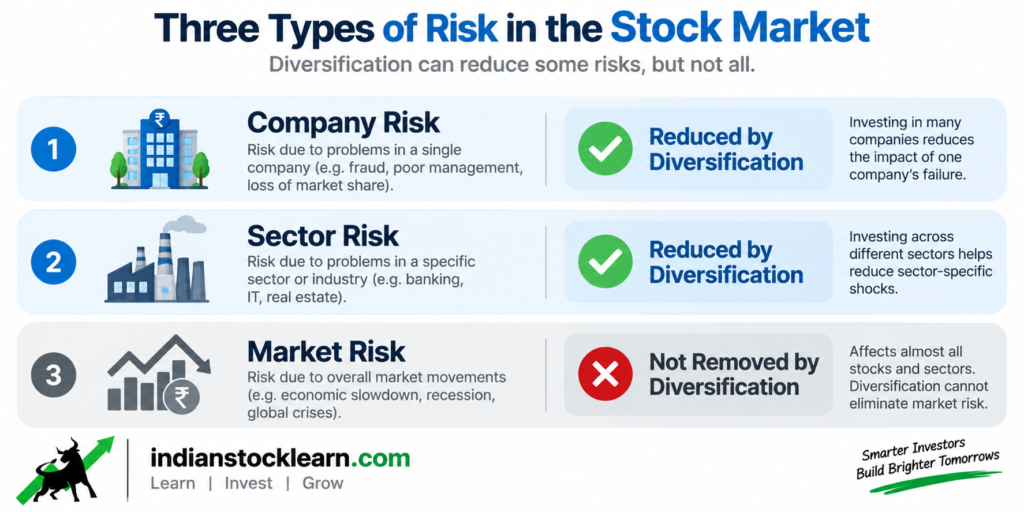
This is the core of why diversification is important: a company can run into trouble that has nothing to do with the broader market – a failed product, a management change, a falling profit margin, a new competitor. Zerodha Varsity describes this as company-specific, or unsystematic, risk – the kind diversification can reduce. Market-wide risk is a different matter and isn’t removed simply by owning more stocks.
Diversification Doesn’t Mean Owning Everything
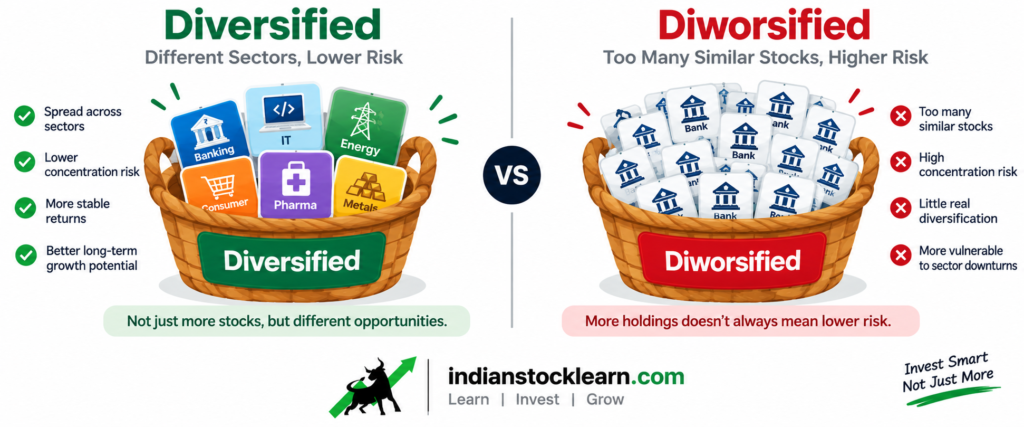
A diversified portfolio doesn’t have to mean owning 50 or 100 stocks. Five IT companies are still exposed almost entirely to the IT sector. Five banks are still exposed to financial-sector conditions. If several holdings tend to rise and fall together, the portfolio may look spread out on paper while behaving like one big bet. What matters is the quality of the spread, not just the count.
How Diversification Works
The clearest way to understand diversification is by looking at where risk actually comes from.
Risk tied mainly to one business – a client loss, a lawsuit, a product recall. Owning several unrelated companies spreads this out.
An entire industry under pressure – rate changes hitting banks, weak global spending hitting IT. Owning multiple sectors reduces dependence on one.
A broad shock – a financial crisis, a geopolitical event – that pulls most stocks down together. Diversification cannot remove this.
Investors can diversify at several levels: across individual companies, sectors, market capitalisations, asset classes, and even countries. Diversifying within Indian equities might mean exposure to financials, technology, energy and consumer businesses. Diversifying across asset classes is broader still – combining equity, debt, gold and other assets whose returns don’t always move in the same direction.
Myth vs Reality: More Stocks Isn’t More Diversification
| Myth | Reality |
|---|---|
| “I own 10 stocks, so I’m well diversified.” | If those 10 stocks are concentrated in one or two sectors, or tend to move together, the portfolio behaves like a much smaller, more concentrated bet than the stock count suggests. |
| “More holdings always means less risk.” | Beyond a certain point, adding more similar investments mainly adds complexity without meaningfully reducing risk – a pattern sometimes called “diworsification.” |
| “Different asset classes always move in opposite directions.” | Correlations between assets can and do change depending on market conditions – equity, debt and gold don’t always offset each other the way textbook examples suggest. |
A ₹1 lakh portfolio split equally across four stocks (₹25,000 each). If one stock falls 40%, that’s a ₹10,000 loss on that stock – but only a 10% hit to the total ₹1 lakh portfolio, assuming the other three don’t move. The same ₹40,000 loss in a single-stock portfolio would have been a full 40% hit.
Real portfolios are more complicated because investments can move together. Four stocks that all rise and fall in sync don’t offer as much protection as four names might suggest. The more useful way to think about it isn’t “more stocks equals more diversification” – it’s “different sources of risk, spread reasonably, equals better diversification.”
Real Stock Market Example
Picture a portfolio with Reliance Industries, TCS, HDFC Bank, ICICI Bank and ITC. These sit in different parts of the economy – energy and retail, IT services, banking, and consumer goods – though the two banks share some common sector exposure.
If global technology spending slows, TCS could be hit harder than a company driven mainly by domestic banking or consumer demand. A portfolio made up entirely of IT companies would feel that slowdown far more sharply than one where IT is just one part of the mix. The same logic runs in reverse for banking-sector pressure.
What About the Nifty 50?
The Nifty 50 is a useful real-world diversification example. It represents 50 companies across major sectors of the Indian economy, weighted by free-float market capitalisation rather than equally. Tracking the Nifty 50 gives exposure to a basket of companies instead of depending on one stock – though that doesn’t mean every constituent moves the same way at the same time. An index fund tracking the Nifty 50 takes this basket approach further, since the fund replicates the index rather than asking the investor to buy each company separately.
The Look-Through Test: Are You Really Diversified?
An investor can hold a Nifty 50 index fund, a large-cap fund and a flexi-cap fund, and feel diversified across three separate products. Look inside each fund’s factsheet, and the top holdings often overlap heavily – the same handful of large companies showing up in all three.
Owning several investment products doesn’t automatically create several independent sources of risk. A stock can be held directly, and again through two or three different funds, without the investor realising the combined exposure to that one company is larger than any single position suggests.
| Investment Held | Underlying Exposure (Example) | Effective Weight |
|---|---|---|
| Direct stock | Company A | 5.0% |
| Index fund | Company A | 1.2% |
| Active large-cap fund | Company A | 0.8% |
| Total effective exposure to Company A | 7.0% | |
This applies to sector labels too. “Large-cap,” “flexi-cap” and “index fund” are product categories, not guaranteed distinct risk exposures – two funds with different names can still be betting on largely the same companies.
Why Investors Use Diversification
Investors diversify to reduce company-specific risk, avoid depending on one sector’s fortunes, and spread exposure instead of betting everything on identifying a single winning stock. SEBI’s investor education material describes diversification within mutual funds in similar terms – spreading investments across a wide range of industries and sectors as a way to manage risk.
Concentration is the flip side of the same idea. An investor can own several stocks and still have most of the portfolio riding on one industry’s outcome – which defeats much of the purpose of spreading out in the first place.
Advantages and Limitations of Diversification
Advantages
- Reduces company-specific risk directly
- Reduces dependence on one sector’s performance
- Can be achieved simply through mutual funds or index funds
- Makes overall portfolio behaviour less extreme in either direction
- Avoids single-stock concentration risk
Limitations
- Cannot remove broad market-wide risk
- Too many holdings can become hard to track and manage
- Similar investments can create hidden sector concentration
- Can dilute the effect of one exceptional performer, not just a poor one
- Does not guarantee higher returns than a concentrated portfolio
Diversification During a Market Crash
The real test of diversification isn’t a normal trading day – it’s a crash. In calm markets, sectors like IT and banking can move with fairly low correlation to each other. During a systemic shock, that relationship often breaks down.
| Type of Shock | What Diversification Typically Does |
|---|---|
| One company’s problem (fraud, failed product) | Strong protection – the rest of the portfolio is largely unaffected |
| One sector under pressure | Partial protection – other sectors can cushion the impact |
| Broad market crash | Limited protection – most equity holdings fall together |
| Liquidity panic (forced, urgent selling) | Correlations across assets can rise sharply, including into “safe” assets |
March 2020 is a widely cited example in Indian markets: portfolios spread across banking, IT, energy and consumer names still fell together over a short period, because panic-driven selling doesn’t discriminate much by sector. That doesn’t mean diversification “failed” – its job was never to prevent every loss.
Diversification limits damage from problems concentrated in one company or one sector. It was never designed to eliminate the risk of a broad market decline – and a diversified portfolio falling during a systemic shock is not evidence that diversification doesn’t work, only evidence of what it was never meant to do.
Your Portfolio Starts Outside Your Demat Account
A securities portfolio spread across five sectors can still sit inside a household that’s heavily concentrated in one industry – just not through stock holdings.
An IT employee holding mostly IT stocks has both future income and investment capital tied to the same industry cycle.
Salary, bonus and portfolio value can all move together if the employer runs into difficulty.
A household can look financially diversified while most of its net worth sits in one property or one city’s real estate market.
Two spouses working in the same industry carry different household risk than income coming from unrelated sectors.
- Diversification means spreading investments across companies, sectors, assets or markets.
- It mainly reduces company-specific and sector-specific (unsystematic) risk.
- It cannot eliminate broad market-wide (systematic) risk.
- Owning many similar stocks doesn’t automatically create good diversification.
- Multiple funds or products can quietly overlap in their underlying holdings – check the look-through exposure, not just the product count.
- During a systemic market shock, correlations across sectors can rise and diversified portfolios can still fall together.
- Diversification in your demat account doesn’t account for concentration in your salary, employer stock or property.
- The Nifty 50 is a real-world example of a diversified index spanning 50 companies across major sectors.
- Mutual funds and index funds can provide diversification through a single investment.
- Diversification does not guarantee profits or protect against every market decline.
Frequently Asked Questions
What is diversification in simple words?
Why diversification is important in investing?
How many stocks are needed for diversification?
Is the Nifty 50 diversified?
Does diversification remove all investment risk?
Can mutual funds provide diversification?
Does owning multiple mutual funds guarantee better diversification?
Does diversification protect a portfolio during a market crash?
Is diversification the same as asset allocation?
Conclusion
Understanding what is diversification comes down to one habit: don’t let one company, sector or bet decide your entire portfolio’s outcome. Spread exposure across different sources of risk instead.
In the Indian stock market, that can mean holding companies across IT, banking, energy and consumer sectors, or using something like a Nifty 50-based investment that already spans 50 companies. Diversification doesn’t make losses disappear, doesn’t guarantee returns, and can’t shield a portfolio from a broad market decline. What it does is reduce dependence on any single investment and limit the damage from company-specific or sector-specific problems.